United Kingdom
 USA
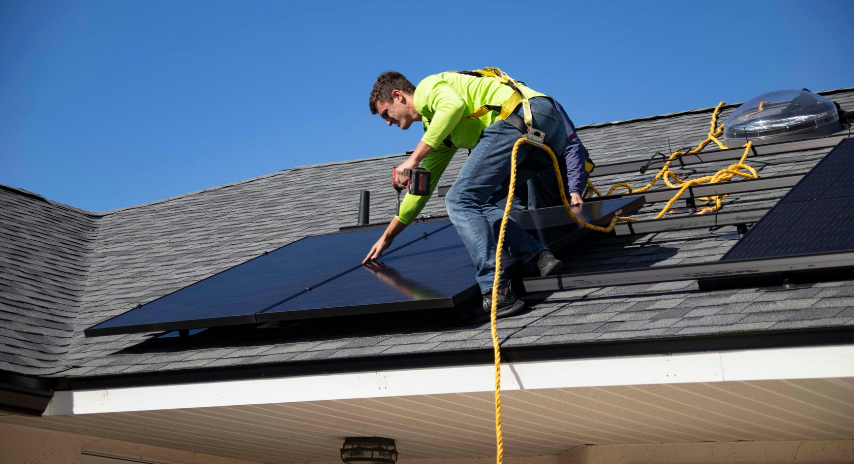
From government schemes and ambitious net-zero goals to reputational gains and cost savings on heating and electricity, there’s plenty of incentive to go green with energy efficient property upgrades.
However, like any significant improvement, eco upgrades can quietly raise your property rebuild value beyond your current coverage, resulting in severe financial vulnerability.
And even if you haven’t made any energy-efficient improvements, new legislation means you’re still at risk!
If you’ve made eco upgrades to your property, you may be underinsured
Property managers and freeholders who have invested in significant block-level energy efficiency upgrades without adjusting their insurance coverage are almost certainly underinsured.
Replacing central gas plant with communal air-source heat pumps, installing roof-mounted solar PV arrays, upgrading EV charging infrastructure, or retrofitting high-performance spandrel insulation and multi-glazed curtain walling adds substantial capital value to the asset. Standard index-linking on an old Reinstatement Cost Assessment (RCA) will not capture these major plant and building envelope upgrades.
While grants or capital expenditure funds may have offset the installation, insurers will only pay out based on the declared sum insured. If a major incident occurs, the shortfall on rebuilding these high-spec communal systems falls entirely on the freeholder or service charge fund.
Why you may be underinsured if you haven’t made green property upgrades – The Future Homes and Buildings Standards
Known collectively as The Future Homes and Buildings Standards, the Future Homes Standard (FHS) and the Future Buildings Standard (FBS), set out new minimum energy efficiency rules for commercial and residential buildings across the UK.
The latest iteration of these standards will come into action at some point in 2025 – although no specific dates have yet been revealed.
Under the FHS (the domestic half of the initiative), all new homes must be produce 75-80% fewer carbon emissions than homes built in accordance with 2013 standards. Similarly, Under the FBS (the commercial half), buildings will be required to meet one of two yet-to-be-agreed-on standards:
- A 27% reduction in carbon emissions compared to the previous standard – this more ambitious option is the government’s preference.
- A 22% reduction in carbon emissions
The Future Buildings Standard (FBS) builds on the 2021 Building Regulations uplift (in force from June 2022), which already required new non-domestic buildings to deliver a 27% reduction in carbon emissions compared to previous Part L standards.
Compliance with both of these standards will be mandatory.
So, what does this have to do with underinsurance for those who own existing commercial and residential structures?
Well, included under the umbrella of “new builds” are rebuilds of older properties – should the existing structure be severely damaged or destroyed.
Let’s say a 10-story residential block built in 2012 suffers catastrophic fire or structural damage. When rebuilding, you cannot simply construct a replica of the 2012 specification. Under current Building Regulations and the Future Homes and Buildings Standards, the replacement structure must comply with modern carbon reduction, thermal performance, and mechanical ventilation mandates.
For a high-rise residential block, meeting modern Part L compliance means incorporating high-efficiency central plant, complex Mechanical Ventilation with Heat Recovery (MVHR) systems, advanced thermal bridging details, and upgraded building envelopes. These mandatory modern standards drive up base reconstruction costs dramatically compared to the original build specification, leaving properties with out-of-date RCAs exposed to massive average clause penalties.
Learn more about the average clause here.
Will there be penalties for non-compliance with the Future Homes and Buildings Standards?
Local authorities have the power to prosecute those carrying out construction projects “in contravention” of the Building Regulations under the Building Act 1984.
As such, construction firms that fail to comply with the Future Homes and Buildings Standards may face fines, and individuals may even face up to two years’ imprisonment. If the property owner is actively commissioning the build, they may be liable for prosecution as the developer of the offending project.
Local authorities are also unlikely to issue a completion certificate for any non-compliant buildings, preventing you from legally occupying the property. No certificate of completion also introduces resale complications, including extensive devaluation.
Furthermore, mortgage lenders and insurers may refuse to be involved unless remedial works are carried out to bring it up to code.
In short, non-compliance is not an option.
Combat underinsurance, not regulation, with an expert Reinstatement Cost Assessment from Cardinus.
By how much could a high-rise block be underinsured under modern standards?
For multi-family residential developments, meeting updated Future Homes and Buildings Standards increases baseline reconstruction costs through high-performance materials, complex plant, and modern compliance requirements.
| Cost Driver / Upgrade | Rebuild Cost Impact | Impact on a £20M High-Rise Rebuild |
| Standard FHS/FBS Compliance (Insulation, MVHR, communal heat networks) | 4% – 8% increase | £800,000 – £1,600,000 shortfall |
| Full Net-Zero Operational Build (PV arrays, central heat pumps, thermal storage) | 10% – 14% increase | £2,000,000 – £2,800,000 shortfall |
| Complex Retrofit Requirements (Post-disaster code alignment) | Up to 15%+ increase | £3,000,000+ shortfall |
On a multi-million-pound high-rise asset, even a modest 4% uplift leaves an uninsured gap of hundreds of thousands of pounds, costs that RMCs, Right to Manage directors, or freeholders would have to cover out-of-pocket.
Learn how often you should have a Reinstatement Cost Assessment.
Protect your block with a modern Reinstatement Cost Assessment
Whether your block has recently undergone major low-carbon retrofits or the building hasn’t had a professional valuation in over three years, relying on estimated sums insured poses a massive financial and fiduciary risk.
As a property manager or freeholder, ensuring your block’s declared value reflects current building regulations and green infrastructure is essential to fulfilling your legal obligations. Contact our team of specialist chartered surveyors today to book an up-to-date Reinstatement Cost Assessment tailored for high-rise residential assets.